What defines the scope and industry significance of the Tunneling And Rock Drilling Equipment Market?
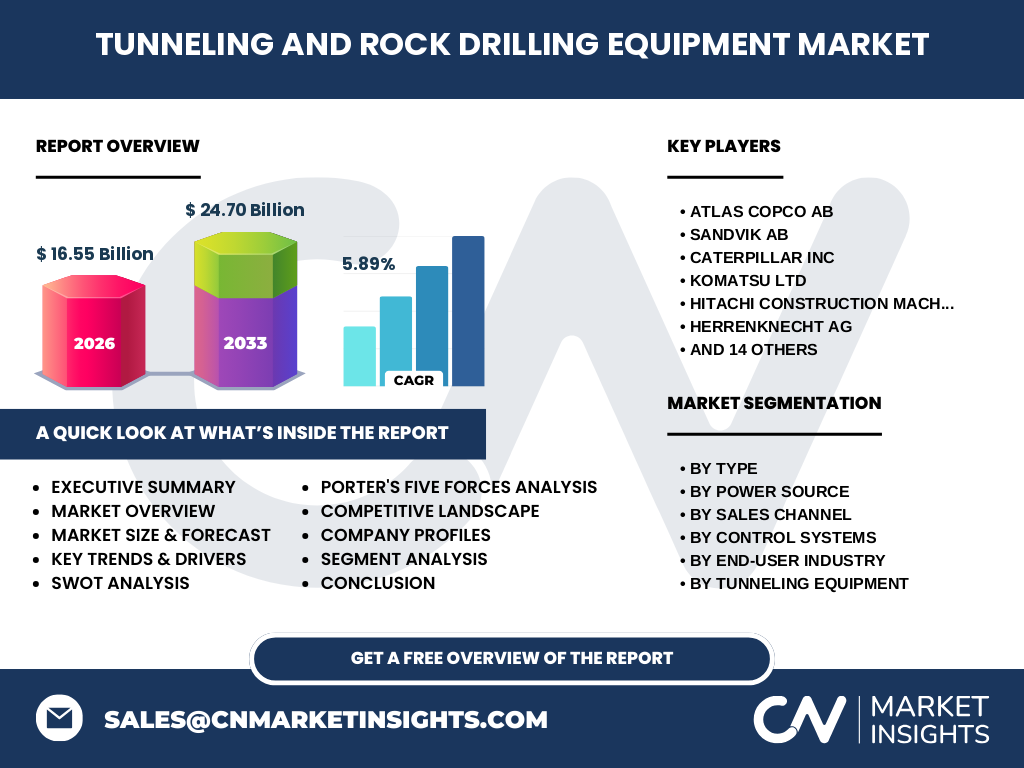
The Tunneling And Rock Drilling Equipment Market represents a critical infrastructure backbone, encompassing specialized heavy machinery like Tunnel Boring Machines (TBMs) and Rotary Drilling Rigs. Valued at 16.55 Billion in 2026, this sector enables essential civil engineering, mining, and renewable energy transitions. It is the primary engine for subsurface connectivity, bridging the gap between raw natural resource extraction and the urbanization of global transport networks.
Structural Growth Drivers and Market Constraints
Growth is propelled by aggressive urban transit expansions and increasing mineral demand. However, the market faces significant logistical hurdles, including high capital expenditure and stringent compliance with safety standards set by bodies like OSHA or ISO. Our analysis indicates that while raw material price volatility for high-grade steel remains a challenge, the massive push for renewable energy pumped-hydro projects serves as a vital counterbalance for equipment manufacturers.
The Shift Toward Automated Tunneling Systems
A pivot toward automated and semi-automated control systems is reshaping site efficiency. Companies like Herrenknecht AG and Sandvik AB are leading this transition, integrating real-time data telemetry into their equipment. This trend reduces human exposure in hazardous rock faces, while simultaneously enhancing drilling precision and reducing wear on critical components, ultimately extending the operational lifecycle of high-value fleet assets.
Assessing the COVID-19 Impact and Recovery Trajectory
The pandemic caused initial, sharp contraction due to supply chain disruptions and localized lockdowns. However, the recovery trajectory has been robust, fueled by government-backed infrastructure stimulus packages globally. Post-2021, the industry successfully transitioned to resilient logistics, with major hubs like the Port of Rotterdam and Shanghai normalizing equipment throughput, setting the stage for steady growth toward the 24.70 Billion mark by 2033.
Competitive Benchmarking and Market Concentration
The market remains highly concentrated, dominated by Tier-1 incumbents such as Atlas Copco AB, Caterpillar Inc, and Komatsu Ltd. These firms leverage deep R&D budgets to dominate, while specialized players like Akkerman Inc and Terratec Ltd focus on niche tunneling projects. Strategic dynamics are increasingly focused on electrification portfolios to meet decarbonization mandates, forcing competitors to rethink their traditional diesel-reliant engine architectures.
Executive Summary: High-Level Market Synthesis
The Tunneling And Rock Drilling Equipment Market is entering a period of sustained acceleration with a CAGR of 5.89% through 2033. By integrating smart technologies with traditional heavy-duty hardware, the industry is overcoming historical labor and safety bottlenecks. Our research highlights that companies prioritizing sustainable power sources and automated control systems will capture the largest share of the projected 24.70 Billion valuation by 2033.
Projected Market Forecast 2027-2033
Based on current macro indicators, the market is set to climb from its 2026 baseline to an impressive 24.70 Billion by 2033. This forecast accounts for sustained demand in the mining and water management sectors. We anticipate that mid-term infrastructure cycles—particularly in the APAC region—will act as the primary catalyst, ensuring the projected 5.89% CAGR remains achievable despite potential global economic fluctuations.
Segmentation Analysis: Breaking Down the Industry
The industry is segmented by Type (Tunneling vs. Rock Drilling), Power Source (Electric, Hydraulic, Diesel), and End-User. Tunnel Boring Machines dominate in scale, while Top Hammer Drills are essential for mining efficiency. The segment breakdown reveals that Rental Services are gaining traction as contractors seek to minimize the financial burden of owning expensive machinery while maintaining project flexibility in volatile markets.
Geographic Distribution and Regional Performance
Geographically, the market is dominated by the Asia-Pacific region, driven by massive urbanization projects in China and India. Europe and North America follow, with mature markets focusing on rehabilitation of aging tunnel infrastructure. Our regional review indicates that localized regulatory frameworks and state-led mining incentives play a decisive role in which power source segments—such as electric-powered drills—experience faster adoption rates in specific localized jurisdictions.
In-depth Regional Review: Emerging Hotspots
We note intense activity in South America and Africa regarding mining resource extraction, which drives demand for percussion drilling equipment. Conversely, European markets are prioritizing zero-emission tunneling, favoring firms like Normet Group Oy. This regional divergence suggests that manufacturers must tailor their product offerings, as high-spec automated rigs are prioritized in advanced economies, whereas high-durability mechanical rigs remain the preference in emerging mineral-rich territories.
Company Profiles and Strategic Positioning
Leading firms are carving distinct paths: Sandvik AB focuses on digitally-integrated mining fleets, while Herrenknecht AG remains the gold standard for massive TBM tunneling. Meanwhile, SANY Group Co Ltd and China Railway Engineering Equipment Group Co Ltd aggressively leverage cost-competitive manufacturing. These players are increasingly competing on Total Cost of Ownership (TCO) rather than initial purchase price, reflecting a shift toward long-term lifecycle service contracts.
Porter's Five Forces Analysis
The industry exhibits high barriers to entry due to intense capital requirements and specialized intellectual property. Buyer power is moderate; while end-users have choices, the technological complexity of machines like TBMs keeps them tied to established OEMs. Competitive rivalry is fierce, intensified by the constant race to deliver autonomous, carbon-neutral drilling solutions that differentiate providers in a crowded global landscape.
SWOT Analysis of the Market Landscape
Strengths include high barriers to entry and strong brand equity of incumbents. Weaknesses involve high sensitivity to raw material cycles and supply chain fragility. Opportunities exist in the renewable energy sector for underground storage solutions. Threats comprise unpredictable shifts in government infrastructure spending and the potential for disruptive green technology mandates that could render traditional diesel-engine equipment obsolete before the end of its projected asset life.
Value Chain Analysis: From Raw Materials to End-Users
The value chain originates with specialty steel and hydraulic component manufacturers. Value is added through high-precision engineering and assembly by OEMs like Caterpillar Inc or Hitachi Construction Machinery. Distribution occurs via Direct Sales or authorized global dealer networks. The final delivery to mining and construction end-users is often supported by post-sales maintenance contracts, which constitute a significant, recurring revenue stream for the major market participants.
Investment Insights and High-Potential Areas
Investors should target companies leading in electrification and remote operation technologies. High-potential areas include the retrofitting of existing machinery with modern sensors to meet new efficiency standards. Furthermore, the water and wastewater treatment segment is an undervalued growth pocket, as urbanization requires massive underground pipe installation, consistently driving demand for small-to-mid-sized tunneling equipment outside of the spotlight-grabbing major transit projects.
Conclusion and Key Takeaways
The Tunneling And Rock Drilling Equipment Market is fundamentally robust, supported by a transition to smarter, cleaner technology. With a market size projected to hit 24.70 Billion by 2033, the industry is transitioning from purely hardware-driven sales to integrated digital service models. Success will ultimately belong to firms that harmonize technical innovation with regional compliance and sustainability demands.
Research Methodology: How Baseline Estimates are Triangulated
Our analysis employs a triangulated research methodology. We combine trade registry data from key industrial zones, interviews with senior procurement officers in mining and construction, and macroeconomic indicators from agencies like the World Bank. This ensures our 16.55 Billion baseline and subsequent forecasts are reflective of real-world equipment deployments, trade flow adjustments, and capital expenditure trends across all major global operational theaters.
Scope of the Report: Coverage Parameters and Limitations
This report covers global Tunneling and Rock Drilling Equipment sales across five end-user industries. It focuses on equipment types from Continuous Miners to Hydraulic Drills. Limitations include the exclusion of small-scale artisan drilling tools and potential variance in localized import-export taxes, which may influence regional pricing structures beyond our controlled forecast. Our data is rigorously vetted for accuracy within the scope of global commercial infrastructure deployments.
Recent Developments and Market Movements
The industry has seen recent strategic partnerships aimed at merging AI-driven navigation with standard TBM chassis. Furthermore, companies like Furukawa Rock Drill Co Ltd and Boart Longyear Ltd have accelerated product launches emphasizing noise reduction and energy efficiency. These developments signal a wider move toward ESG-compliant job sites, directly impacting the procurement criteria for major public-sector projects worldwide in the 2026-2027 fiscal period.